Roof Insurance Claims
After a storm, the claim is yours and the decision is your insurance company's. What GemSco does is make sure the damage on your roof is inspected, photographed and estimated in writing, so you file with a clear record.
Schedule Your Roofing Inspection Today
Fill out the information below and we’ll reach out to complete your estimate as soon as possible!
What a roofer can and cannot do in a claim
Coverage depends on your policy and on the insurance company's decision. No contractor can promise that a claim will be paid or how much it will pay. What a roofer can do is inspect the roof, document the damage with photos and give you a written estimate for the repair or replacement.
In Texas, a roofing contractor cannot act as your public adjuster or negotiate the claim on your behalf, and cannot waive or absorb your deductible. Any company that offers to cover your deductible is offering something the law does not allow. If you want someone to represent you in the claim, that is the role of a licensed public adjuster; our blog explains how public adjusters can help.
How the process usually works
Protect the home
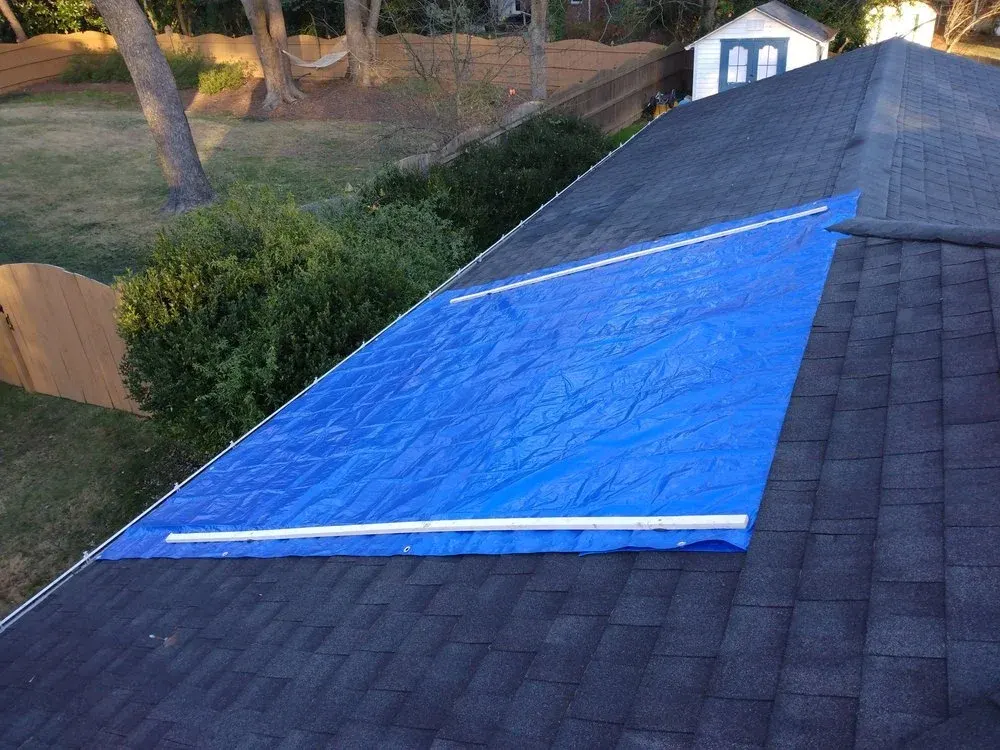
Take reasonable steps to stop further damage and keep receipts. See emergency roof repair.
Inspection and photos
GemSco inspects the roof and photographs the damage on each slope, flashing, vents and gutters.
Written estimate
You receive a written estimate describing the work needed to repair or replace the roof.
You file the claim
You contact your insurance company, report the date of the storm and share the photos and estimate if you choose.
Adjuster inspection
The insurer sends an adjuster who inspects the roof and prepares the insurer's own estimate.
Insurer's decision
The insurance company decides what the policy covers. You then decide how to proceed with the work.
Terms you will hear
Deductible
The part of the loss you pay before coverage applies. Many Texas policies have a separate deductible for wind and hail, sometimes a percentage of the home's insured value.
ACV
Actual cash value: the cost to replace the roof minus depreciation for age and wear. Some policies pay roofs on this basis.
RCV
Replacement cost value: the cost to replace the roof with similar materials, without deducting depreciation.
Recoverable depreciation
Under some RCV policies, part of the payment is held back until the work is completed and documented.
Cosmetic damage exclusion
Some policies exclude damage that affects appearance but not function, such as dents on metal. Check whether yours has one.
Documentation that helps
The date and time of the storm.
Photos of the roof, gutters, vents and any damage inside the home.
Photos of hail on the ground or damage to cars, fences and outdoor equipment, if you took them.
Receipts for anything you did to protect the home.
A copy of your policy, including the declarations page and any endorsements.
The written estimate and inspection photos from your roofer.
If your claim is denied or underpaid
A denial is not always the final word. Ask the insurer for the reason in writing and compare it with your policy and with the documentation from the inspection. Our blog covers why roof claims get rejected, what to do if your claim is denied and how to appeal a denied claim.
Whatever the outcome, you choose what happens to your roof. If the damage is from hail, see hail damage roof repair; for wind and other storm damage, see roof storm damage. If you pay for part of the work yourself, roof financing explains what to compare.
Who is inspecting your roof
GemSco is family owned, fully licensed and insured, with more than 20 years of experience and elite contractor status with Owens Corning and GAF. We inspect and document storm damage on homes and commercial buildings in Houston, DFW, Austin, San Antonio and surrounding areas, including Dallas and Houston. Estimates are free.
Frequently Asked Questions
Will my insurance pay for a new roof?
That depends on your policy and on the insurance company's decision. Factors include the cause and extent of the damage, the age of the roof, your deductible and whether the policy pays on ACV or RCV. GemSco inspects, photographs the damage and gives you a written estimate so you file with a clear record.
How long do I have to file a roof claim in Texas?
Deadlines are set by your policy and by Texas law, and they can be shorter than you expect. Read the section of your policy on reporting a loss, or ask your agent. Filing soon after the storm also helps, because fresh damage is easier to document and link to a specific date.
Can GemSco pay or waive my deductible?
No. Texas law does not allow a roofing contractor to waive, rebate or absorb an insured's deductible. The deductible is your share of the loss under your policy. Be cautious with any contractor who offers to cover it, because that offer is not legal.
Should I call my insurer or a roofer first?
Many homeowners get an inspection first, so they know whether there is damage worth reporting and have photos and a written estimate when they call. Check your policy's reporting requirements, though, and do not let an inspection delay a report past any deadline.
We’re Here to Help!
GemSco Roofing & Solar serves Houston, DFW, Austin, San Antonio and surrounding areas. We’re family owned and fully licensed and insured.